Showing posts with label JPMORGAN. Show all posts

Monday, June 10, 2024

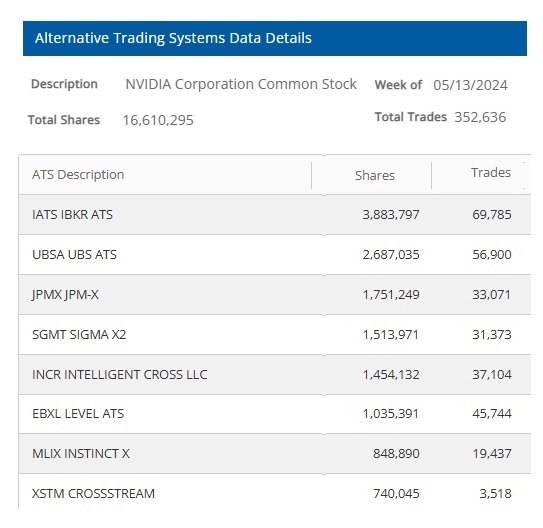
Nvidia Hit a $3 Trillion Market Cap Last Week; Dark Pools Are Making Over 300,000 Trades in the Stock Weekly


SUBSCRIBE TO THIS NEWSLETTER TO RECEIVE TIMELY REPORTS!

PLEASE READ & SHARE! THIS IS AN ISSUE BEING OVERLOOKED & IGNORED!


Nvidia Hit a $3 Trillion Market Cap Last Week; Dark Pools Are Making Over 300,000 Trades in the Stock Weekly

By Pam Martens and Russ Martens: June 10, 2024 ~
The much-hyped artificial intelligence chipmaker, Nvidia (ticker NVDA), reached a market cap of $3 trillion on Thursday, beating out Apple as the second most valuable company, just behind Microsoft. This morning, Nvidia’s 10-for-1 stock split will become effective, reducing its share price to, ideally, entice more retail investors.

Year-to-date, Nvidia’s stock price is up 144 percent through the closing bell on Friday.

The company was founded on April 5, 1993 and lived the bulk of its existence in obscurity until a New York Times article appeared on September 1, 2017 with this headline: “Why a 24-Year-Old Chipmaker Is One of Tech’s Hot Prospects.”

Browsing the company’s prolific newsroom reveals no shortage of bold pronouncements. A June 2 press release carries this seismic prediction:

“The next industrial revolution has begun. Companies and countries are partnering with NVIDIA to shift the trillion-dollar traditional data centers to accelerated computing and build a new type of data center — AI factories — to produce a new commodity: artificial intelligence….”

Our first instinct was to take a look to see how much trading in Nvidia’s shares is occurring in Dark Pools – non-transparent trading platforms operated by some of the biggest trading houses on Wall Street (which are also, insanely, allowed to own some of the largest federally-insured U.S. commercial banks which hold trillions of dollars in deposits).

Wall Street’s self-regulator, FINRA, began providing some Dark Pool data back in 2014. Unfortunately, the trading data for each Dark Pool and the respective stock it is trading is lumped together for the entire week, not by the minute or hour or day, and the data arrives to the public two weeks late for big cap stocks and four weeks late for smaller companies.

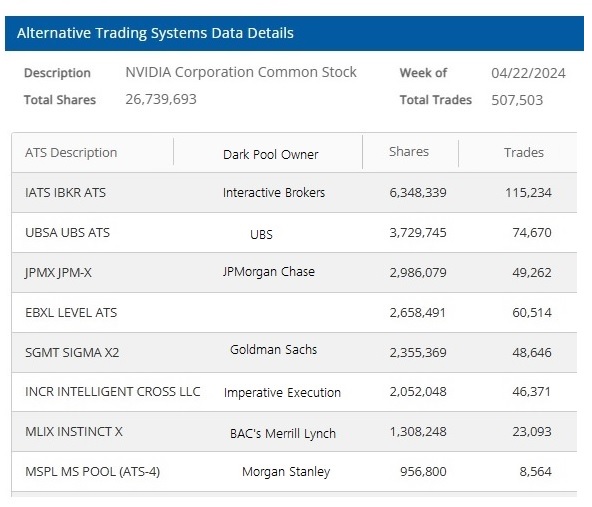
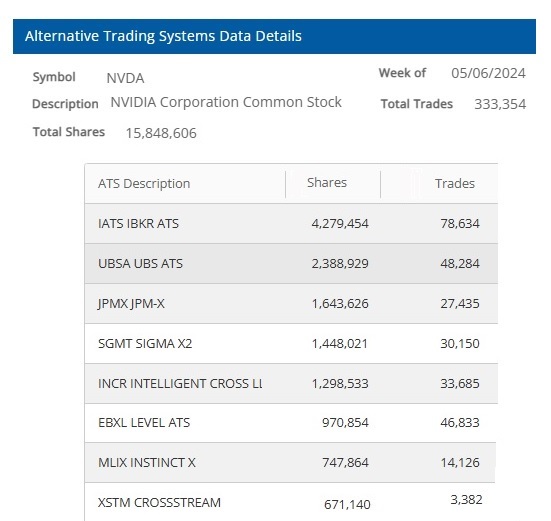
The charts below show the top eight Dark Pools that made the largest number of trades in Nvidia’s stock for a recent three weeks that FINRA has made trading data available. The Dark Pool owned by Interactive Brokers has consistently been the largest trader of Nvidia’s shares. In second and third place has been global banking behemoths UBS and JPMorgan, respectively. Dark Pools owned by other global trading powerhouses, Goldman Sachs, Morgan Stanley, and Bank of America’s Merrill Lynch, have also ranked in the top eight.

Interestingly, JPMorgan has shelled out $250 million in fines to the Office of the Comptroller of the Currency; $98.2 million to the Federal Reserve and $100 million (netted down from $200 million) to the Commodity Futures Trading Commission since March for failing to provide proper surveillance of “billions” of trades. The regulators were deafeningly silent on whether JPMorgan’s Dark Pools were involved in these infractions. (See here, here and here.)

Following the stock market crash of 1929 (which ushered in the Great Depression), the U.S. Senate Banking Committee conducted an exhaustive investigation into the trading structure and trading practices on Wall Street. The titans of Wall Street were put under oath and troves of documents were subpoenaed. The Senate investigations focused on the collusive dealings of “pools.” The 1930s Senate investigation found the following:

“A pool, according to stock exchange officials, is an agreement between several people, usually more than three, to actively trade in a single security. The investigation has shown that the purpose of a pool generally is to raise the price of a security by concerted activity on the part of the pool members, and thereby to enable them to unload their holdings at a profit upon the public attracted by the activity or by information disseminated about the stock. Pool operations for such a purpose are incompatible with the maintenance of a free and uncontrolled market.”

The Senate Banking Committee of 1934 concluded as follows:

“The conclusion is inescapable that members of the organized exchanges who had a participation in or managed pools, while simultaneously acting as brokers for the general public, were representing irreconcilable interests and attempting to discharge conflicting functions. Yet the stock exchange authorities could perceive nothing unethical in this situation.”

As Wall Street On Parade has previously reported, U.S. regulators are not only allowing these quasi stock exchanges to operate in darkness, they are allowing Goldman Sachs, Bank of America Merrill Lynch, JPMorgan Chase and others to trade their own publicly-traded bank stocks in their own Dark Pools.

The U.S. stock market, once the envy of the world, remains dangerously opaque today, in no small part because of the sick revolving door structure between Wall Street and its regulators.

Congress does not feel compelled to tackle the problem because corporate media has chosen to ignore the mushrooming problem. Even after bestselling author and Wall Street veteran, Michael Lewis, went on the heavily watched 60 Minutes program on CBS in 2014 and told viewers that “The United States stock market, the most iconic market in global capitalism is rigged,” Congress and the SEC have continued to dance around the problem.

Until the public demands change, the darkness will continue to deepen in increasingly dangerous ways.
WALL STREET ON PARADE

60 Minutes Sanitizes Its Report on High Frequency Trading


By Pam Martens: April 1, 2014
Floor of the New York Stock Exchange as Featured in 60 Minutes Report on High Frequency Trading

Two of the chief culprits of aiding and abetting high frequency traders, the New York Stock Exchange and the Nasdaq stock exchange, failed to come under scrutiny in the much heralded 60 Minutes broadcast on how the stock market is rigged.

This past Sunday night, 60 Minutes’ Steve Kroft sat down with noted author Michael Lewis to discuss his upcoming book, “Flash Boys,” and its titillating revelations about how high frequency traders are fleecing the little guy.

Kroft says to Lewis: “What’s the headline here?” Lewis responds: “Stock market’s rigged. The United States stock market, the most iconic market in global capitalism is rigged.”

Kroft then asks Lewis to state just who it is that’s rigging the market. (This is where you need to pay close attention.) Lewis responds that it’s a “combination of these stock exchanges, the big Wall Street banks and high-frequency traders.” We never hear a word more about “the big Wall Street banks” and no hint anywhere in the program that the New York Stock Exchange and Nasdaq are involved.

60 Minutes pulls a very subtle bait and switch that most likely went unnoticed by the majority of viewers. In something akin to its own “Flash Boys” maneuver, it flashes a photo of the floor of the New York Stock Exchange as Kroft says to the public that: “Michael Lewis is not talking about the stock market that you see on television every day. That ceased to be the center of U.S. financial activity years ago, and exists today mostly as a photo op.”

That statement stands in stark contrast to the harsh reality that the New York Stock Exchange is one of the key facilitators of high frequency trading and making big bucks at it.

In this Google cache of a promotional piece aimed at high frequency traders, the New York Stock Exchange explains how it is offering a “fully managed co-location space next to NYSE Euronext’s US trading engines in the new state-of-the-art data center.” Who is it for? The NYSE says it is for “High frequency and proprietary trading firms, hedge funds and others who need high-speed market access for a competitive edge.” More eye-popping details on how the New York Stock Exchange is arming high frequency traders in Mahwah, New Jersey against the little folks who can’t afford tens of thousands of dollars a year for a “competitive edge” are provided on its web site here. (The closer a high frequency trader’s computers are located to the New York Stock Exchange’s main computers, the faster their trades are executed.)

The Securities and Exchange Commission knows full well this is going on. Just this past December 24, the SEC filed this rule change in the Federal Register, announcing that the New York Stock Exchange was changing its pricing for some of its co-location services and computer cabinets for outside users. Like some kind of a half-off sale at Macy’s, the NYSE says it will offer: “a one-time Cabinet Upgrade fee of $9,200 when a User requests additional power allocation for its dedicated cabinet such that the Exchange must upgrade the dedicated cabinet’s capacity. A Cabinet Upgrade would be required when power allocation demands exceed 11 kWs. However, in order to incentivize Users to upgrade their dedicated cabinets, the Exchange proposes that the Cabinet Upgrade fee would be $4,600 for a User that submits a written order for a Cabinet Upgrade by January 31, 2014…”

The Federal Register notice also shines light on some pricing comparisons between what the NYSE is offering high frequency traders versus the Nasdaq stock market, writing: “The Exchange also believes that the Cabinet Upgrade fee is reasonable because it would function similar to the NASDAQ charges for comparable services. In particular, NASDAQ charges a premium initial installation fee of $7,000 for a ‘Super High Density Cabinet’ (between 10 kWs and 17.3 kWs) compared to $3,500 for other types of cabinets with less power.The Exchange charges only one flat rate for its initial cabinet fees ($5,000), regardless of the amount of power allocation.”

Congress is equally aware of what is going on. As far back as October 28, 2009, the U.S. Senate Banking committee took testimony from Larry Leibowitz, head of technology at the NYSE on the fact that it was offering co-location to outside trading firms. Neither the Flash Crash of 2010 or confidence-busting trading “glitches” since then have roused Congress and the SEC from their slumber.

Another opportunity emerges in the 60 Minutes broadcast for Kroft to call out the New York Stock Exchange or Nasdaq for their practices. As Kroft explains how this young former trader from the Royal Bank of Canada, Brad Katsuyama, figured out how high frequency traders were gaming the market and made appointments with institutional investors to share his insights, Kroft says “and some of the most famous names in the American stock market heard the pitch.” At this exact moment a photo of the exterior of the New York Stock Exchange flashes across the screen, giving the impression that the NYSE is some poor, naïve victim of a cartel of high frequency traders.

What is also preposterous about this 60 Minutes segment is that it deals exclusively with gaming the system through miles of fiber optic cable. That is so yesterday, according to the Futures Industry magazine. On January 24 of last year, the publication wrote that “High frequency traders can use wireless to connect to data sources or exchanges about 1.5 times faster than through fiber optics, enabling them to quote prices at tighter bid-ask spreads than rivals or execute trades more quickly than other firms. Such are the potential competitive advantages, however, that many projects are pursued behind a veil of silence.”

The article noted that San Diego-based NexxCom Wireless was building a millimeter wave network between New York, London and Frankfurt and considering connections to Zurich and Milan with the potential to add Stockholm and Moscow.

Within less than 24 hours of the big splash made by the 60 Minutes broadcast, the Wall Street Journal reported that the FBI was all over the problem and had been for a year. The question, of course, is – will anyone ever acknowledge the key role being played by the New York Stock Exchange and Nasdaq.

Related Article:

60 Minutes Takes a Pass On Wall Street’s Secret Spy Center


WALL STREET ON PARADE

Wednesday, March 6, 2024

New York Community Bancorp Was JPMorgan’s Top Regional Bank Pick for 2024; It’s Lost 73 Percent Y-T-D and Had Its Deposit Rating Downgraded to Junk


SUBSCRIBE TO THIS NEWSLETTER & RECEIVE TIMELY REPORTS!


New York Community Bancorp Was JPMorgan’s Top Regional Bank Pick for 2024; It’s Lost 73 Percent Y-T-D and Had Its Deposit Rating Downgraded to Junk

By Pam Martens and Russ Martens: March 5, 2024 ~

New York Community Bancorp’s tumultuous share price descent began on January 31 when the bank filed an 8K form with the SEC indicating a $260 million net income loss in the fourth quarter; a dividend cut from 17 cents to 5 cents; and a $552 million provision for credit losses on commercial real estate. (Year-to-date, the company’s share price has lost 73 percent of its market value. Yesterday, its shares closed at $2.73, down 23 percent from the prior trading session on Friday, when the shares had lost 26 percent. )

Somehow, JPMorgan banking analyst Steven Alexopoulos was able to swat the gargantuan warning signs of January 31 away like a pesky gnat on an otherwise perfect day. On February 1, Alexopoulos penned a missive recommending that investors “take advantage of this valuation and accumulate shares on this weakness.” To drive home his strong buy recommendation, he wrote: “Not only do we maintain our Overweight rating, but NYCB remains our top pick for 2024.”

JPMorgan’s bank analyst call on NYCB is turning out to be another embarrassing black mark at JPMorgan Chase, a bank that seems to have enshrined scandals and felony charges as an integral part of its mega bank business model.

JPMorgan’s strong buy rating on New York Community Bancorp came a mere 34 days ago. Here’s what has happened since then:

On February 6, Moody’s downgraded the bank’s credit rating to junk. Moody’s also warned that a third of the bank’s deposits lack FDIC insurance.

On February 29, NYCB made new filings with the SEC, this time announcing that its President and CEO, Thomas R. Cangemi, was being replaced by the Executive Chairman of the Board, Alessandro (Sandro) DiNello. In a separate filing, NYCB announced alarming “material weaknesses,” writing as follows:

“…as part of management’s assessment of the Company’s internal controls, management identified material weaknesses in the Company’s internal controls related to internal loan review, resulting from ineffective oversight, risk assessment and monitoring activities. Although assessment of the Company’s internal controls is not yet complete, the Company expects to disclose in the 2023 Form 10-K that its disclosure controls and procedures and internal control over financial reporting were not effective as of December 31, 2023. The Company’s remediation plan with respect to such material weaknesses is expected to be described in the 2023 Form 10-K.”

“Material weaknesses” are two words that credit rating agencies never want to read in a deposit-taking bank’s filings with the Securities and Exchange Commission. After markets closed last Friday, Moody’s cut the deposit rating on NYCB’s commercial bank by four notches, moving it deep into junk territory.

That can’t have gone over well with the folks holding large amounts of uninsured deposits at the bank. (The Federal Deposit Insurance Corporation (FDIC) insures commercial bank accounts up to $250,000 per depositor, per bank. Corporations and institutions frequently hold sums much greater than that at commercial banks.)

On March 28 of last year, the Chair of the FDIC, Martin Gruenberg, delivered a report to the Senate Banking Committee on why Silicon Valley Bank and Signature Bank had failed last year. Among numerous problems, he noted the following:

“In the immediate aftermath of the failure of SVB [Silicon Valley Bank] and Signature Bank, some preliminary lessons can be identified. A common thread between the failure of SVB and the failure of Signature Bank was the banks’ heavy reliance on uninsured deposits. As of December 31, 2022, Signature Bank reported that approximately 90 percent of its deposits were uninsured, and SVB reported that 88 percent of its deposits were uninsured. The significant proportion of uninsured deposit balances exacerbated deposit run vulnerabilities and made both banks susceptible to contagion effects from the quickly evolving financial developments. One clear takeaway from recent events is that heavy reliance on uninsured deposits creates liquidity risks that are extremely difficult to manage, particularly in today’s environment where money can flow out of institutions with incredible speed in response to news amplified through social media channels.”

Yesterday, we wrote about the insightful investigation by financial watchdog, Better Markets, into how New York Community Bancorp ended up in such a mess. Better Markets’ researchers found the following:

“In late 2022 and early 2023, the federal banking regulators inexplicably approved not one, but two, mergers for NYC Bancorp in rapid succession. First, in December 2022, Flagstar was acquired by NYC Bancorp and at the same time Flagstar acquired [New York Community Bank]. Then, only about 100 days later, Flagstar was selected as the winning bidder by the FDIC to acquire the failed Signature Bank (‘Signature’). A bank acquiring and integrating any one of these transactions in isolation would be challenging under the best of circumstances, it is inexplicable that the banking regulators allowed them in tandem under extremely stressed conditions.”

And this:

“…over the course of just two quarters, Flagstar’s two acquisitions quadrupled its asset size, from $25 billion on September 30, 2022, to $123 billion on March 31, 2023. It also more than doubled its employee count, from about 2,800 in September 2022 to 6,800 in March 2023.”


https://wallstreetonparade.com/2024/03/new-york-community-bancorp-was-jpmorgans-top-regional-bank-pick-for-2024-its-lost-73-percent-y-t-d-and-had-its-deposit-rating-downgraded-to-junk/


Sunday, September 3, 2023

Former FBI Agent Prepared to Testify that JPMorgan Had Jeffrey Epstein Account for 28 Years – Not 15 Years – and “Impeded” Criminal Investigation of Epstein

SUBSCRIBE TO THIS NEWSLETTER TO RECEIVE TIMELY REPORTS 


Former FBI Agent Prepared to Testify that JPMorgan Had Jeffrey Epstein Account for 28 Years – Not 15 Years – and “Impeded” Criminal Investigation of Epstein

By Pam Martens and Russ Martens: August 2, 2023 ~

JPMorgan Building FacadeOn July 24th and 25th, the Attorney General’s Office for the U.S. Virgin Islands filed dozens of documents in the court case it has launched against the largest federally-insured bank in the United States – JPMorgan Chase – in a U.S. district court in Manhattan. A quick glance at the giant blur of filings indicated that the vast majority had been filed under seal. (See a partial screen shot here.) The U.S. Virgin Islands is credibly alleging in its lawsuit that JPMorgan Chase “actively participated in Epstein’s sex trafficking venture” where dozens of underage girls were sexually assaulted by Epstein or his rich pals.

Wall Street On Parade has learned over the years to deeply scrutinize anything that is happening in the federal district court in the Southern District of New York, where Wall Street has kept critical information about its serial crimes against the American people hidden behind a dark curtain of protective orders, sealed documents, and non-transcribed conferences with the judge – exactly what is happening in this case.

Shaun O'Neill, Retired FBI Agent of 23 Years

Shaun O’Neill, Retired FBI Agent of 23 Years

As we scrutinized the dozens of sealed documents entered on July 24th and 25th, we noticed that a few here and there were not sealed. We opened those documents and were stunned to see that one was an expert report written by a former FBI agent of 23 years, Shaun O’Neill, who had made a finding that JPMorgan Chase had “impeded” the federal criminal investigation of Epstein. Ostensibly, this expert report is going to be entered into evidence in the jury trial currently scheduled in the matter for October 23.

The document had a heading at the top of each page that read: “Highly Confidential – Subject to Protective Order.” However, the notation on the docket was that it was now being presented as a “redacted” document. We called the court deputy to be certain that the media was allowed to quote from the unredacted parts of the document. We were assured that we could.

A major revelation in the document is that former FBI agent O’Neill had been allowed to read the deposition given in the case by William Langford, an anti-money-laundering (AML) executive at JPMorgan Chase who had previously worked for the Financial Crimes Enforcement Network (FinCEN) – the very agency where Suspicious Activity Reports (SARs) are supposed to be filed by banks like JPMorgan Chase when they handle massive cash withdrawals for people like Jeffrey Epstein.

According to O’Neill, Langford indicates in his deposition that Epstein became a JPMorgan client in 1985, not in 1998, the date that most major news media has heretofore reported and JPMorgan has not publicly corrected.

Jamie Dimon, Chairman and CEO, JPMorgan Chase

Jamie Dimon, Chairman and CEO, JPMorgan Chase

Jamie Dimon, the Chairman and CEO of JPMorgan Chase, testified in his deposition that Epstein “was no longer a client after 2013….” That assertion now looks increasingly suspect. An Epstein financial statement from J.P. Morgan Securities, the brokerage and trading division of JPMorgan Chase, dated March 31, 2014, shows Epstein sold over $667,000 in securities at the firm in 2014. That statement has been entered on the docket as an exhibit.

In addition, on Monday of this week, Linda Singer, a lawyer at law firm MotleyRice, which is representing the U.S. Virgin Islands, revealed in a letter to the presiding judge, Jed Rakoff, that “JPMorgan handled more than $1.1 million in payments from Epstein to girls or women—many with Eastern European surnames—after Epstein was terminated by JPMorgan, including over $320,000 in payments to numerous individuals for whom JPMorgan had not previously identified payments.”

Not to put too fine a point on it, but the bank could not have made payments from Epstein to anyone, unless he still had an account with money in it at some part of the bank. And, if Epstein had an account at any part of the bank, he was still a customer. He might have been flagged as a high-risk customer; he might have had his trading or transactions restricted; but he was still a customer.

Also throwing doubt on the veracity of JPMorgan firing Epstein in 2013 is a supplemental response to interrogatories that JPMorgan itself made with the court. It revealed that Justin Nelson, a banker at JPMorgan, had visited Epstein’s townhouse in Manhattan, sometimes with colleagues, from 2012 through 2017. The filing stated:

“Justin Nelson met with Epstein at his Manhattan townhouse on November 20, 2012; January 15, 2013; April 4, 2013 with Thomas McGraw; on April 24, 2013 with David Frame and Paul Barrett; June 6, 2013 with Chris French; May 8, 2014; December 3, 2014; May 4, 2015; September 29, 2015; November 19, 2015; December 14, 2015 with Carolyn Reers; February 14, 2017. In January 2016 he went to the Zorro Ranch…”

Zorro Ranch was the name of the expansive residence that Epstein maintained in New Mexico, which was also involved in his sex-trafficking ring according to Epstein’s victims.

In addition to JPMorgan Chase making transfers of hundreds of millions of dollars from Epstein’s accounts to his victims, accomplices and recruiters of young girls, the U.S. Virgin Islands has stated in a court filing that “Between September 2003 and November 2013, or approximately ten years, JPMorgan handled more than $5 million in outgoing cash transactions for Epstein.”

Linda Singer, Attorney at MotleyRice

Linda Singer, Attorney at MotleyRice

It was the bank’s failure to report that hard cash flowing out of Epstein’s accounts to law enforcement that helped FBI agent O’Neill reach his conclusion that JPMorgan Chase had impeded a federal criminal investigation. Epstein was, after 2008, a registered sex offender with a documented history of sex trafficking in Palm Beach County. After giving Epstein a sweetheart deal in 2008, the Department of Justice indicted Epstein in July 2019 for sex trafficking. He died in his jail cell in Manhattan just over a month later while awaiting trial. His death was ruled a suicide by the New York City Medical Examiner.

JPMorgan’s awareness of Epstein’s history has been overwhelmingly documented with a vast array of internal emails produced in discovery by the bank.  O’Neill wrote the following in his report:

“Epstein was able to withdraw large amounts of cash from his JPMC accounts for years [Redacted]. In the year 2003, Epstein was able to withdraw highly suspicious amounts of cash totaling $175,311. In 2004, he withdrew $840,000. In 2005, he withdrew $904,337. In 2006, he withdrew $938,625. In 2007, he withdrew $526,000. In 2008, he withdrew $469,000. In 2009, he withdrew $165,011. In 2010, he withdrew $253,397. In 2011, he withdrew $260,000. In 2012, he withdrew $290,000. In 2013, he withdrew $197,152.”

The bank knew, or should have known, that dozens of Epstein’s young victims had come forward with the same set of facts: that he paid them cash in the amounts of $200 to $1,000 for a “massage” that quickly became a sex assault.

O’Neill writes further:

“Human trafficking under U.S. law was transformed with the enactment of the Trafficking Victims Protection Act (the TVPA) in 2000. The TVPA equipped law enforcement, prosecutors and victim advocates with new tools and resources to mount a comprehensive and coordinated strategy to combat modern forms of slavery both domestically and internationally…

“In reference to sex trafficking of a minor with great relevance to the numerous victims at the hands of Jeffrey Epstein, minors need not demonstrate force, fraud, or coercion were used against them to induce them to engage in a commercial sex act. Rather, U.S. law has firmly established that minors cannot consent to commercial sex. Additionally, there is recognition that many forms of human trafficking do not involve force but rather occur through psychological manipulation against victims.”

O’Neill also indicated that “Based on the review of the 17 victim statements contained within the July 25, 2006 Palm Beach Police Department Incident Report, more than ten victims were under the age of 18. The elements of child sex trafficking were present as the allegations referenced a commercial sex act involving a minor and there is no such thing as a ‘child prostitute.’ The allegations reflected a textbook definition of human trafficking.”

O’Neill directly lays the blame for the expansion of Epstein’s sex trafficking ring at the feet of JPMorgan Chase, writing:

“Had JPMC cooperated with federal law enforcement and [Redacted]….Epstein would have been federally charged at a much earlier date. He likely would not have received the Florida Non-Prosecution Agreement, and he would have been imprisoned for the sex trafficking and money laundering crimes that he committed at an earlier time, thereby shrinking his overall list of victims.”

This is a devastating assessment of a bank that in 2014 was charged with two criminal felony counts by the U.S. Department of Justice for looking the other way at money laundering in the business account the bank maintained for Bernard Madoff.  Madoff’s account at the bank was used for decades in the largest Ponzi scheme in U.S. history. The bank told U.K. authorities that it suspected Madoff of running a Ponzi scheme. It kept that information away from U.S. regulators and failed to file the legally mandated Suspicious Activity Reports with FinCEN.

Jamie Dimon was the Chairman and CEO at JPMorgan Chase at the time the Justice Department brought the Madoff charges. The bank has been charged with an additional three felony counts by the Justice Department since then. The bank has admitted to all five felony counts. The Board of Directors of the bank has kept Dimon at the helm despite this unprecedented crime spree.

The nagging question for all Americans is why is this case against JPMorgan Chase being brought as a civil lawsuit by the U.S. Virgin Islands instead of as a criminal case against JPMorgan Chase by the U.S. Department of Justice. After the DOJ and the Florida State Attorney’s Office destroyed their reputations by allowing Epstein to get a non-prosecution agreement and a cozy work release deal in Palm Beach County in 2008, where Epstein’s limo driver took him to his office each day for the majority of his 13 months of “incarceration,” why is the DOJ standing down now on filing charges against the bank that functioned as the central cash conduit for this international sex trafficking ring?

https://wallstreetonparade.com/2023/08/former-fbi-agent-prepared-to-testify-that-jpmorgan-had-jeffrey-epstein-account-for-28-years-not-15-years-and-impeded-criminal-investigation-of-epstein/


Tuesday, February 28, 2023

Rupert Murdoch rats out Kushner on Trump collusion ***WISCONSIN APRIL 4****


atAdvocacy

OD Action is now atAdvocacy!

Demand Fox News suspend Tucker Carlson for calling for violence against teachers and LBGTQ+ people!

Today’s Action: Tell The New York Times to stop their right-wing, anti-trans bias!

Daily Dose of Democracy:

photo
Rupert Murdoch gave Jared Kushner "confidential information" about Biden's 2020 ads before they were public

The Fox News magnate allegedly delivered secret information to Jared Kushner about Joe Biden's political ads and debate strategy in an effort to tip the scales in Trump's favor. What else did Murdoch and Fox funnel to the Trump team behind the scenes? It's time for a full federal investigation.

Take Action: Demand the Justice Department investigate Jared Kushner for shady investments from the Saudis!


photo
VIDEO OF THE DAY: Fox News' Rupert Murdoch sinks his own network in bombshell deposition

The arch-villain of global news media admitted under oath that hosts on his right-wing network explicitly endorsed false claims about the 2020 election being stolen — proving once again that Fox News is a direct threat to American democracy.

Take Action: Tell the Senate to confirm Biden's judges ASAP!


photo
The next presidential election could be at stake

Wisconsin Democrats: With the balance of the state's Supreme Court on the line, progressive champion Judge Janet Protasiewicz and radical MAGA extremist Dan Kelly have emerged as the nominees for the vacated all-important swing seat. This April 4th election is an absolute MUST-WIN for everything we hold dear — abortion rights, LGBTQ rights, the right to vote, and potentially even a free and fair election for the next President of the United States. Can you chip in to make sure Janet has the resources she needs to win and flip Supreme Court of the most important swing state to a progressive majority?


John Fetterman "on path to recovery," will be out for more weeks
The Democratic senator recently checked himself into a hospital to seek help for clinical depression — an incredibly brave move that was immediately exploited and criticized by craven right-wingers. Fetterman's spokesperson has now revealed that the freshman senator is improving, is constantly speaking with his family and staff, and will be back in action in a few weeks.

Take Action: Tell Congress: Pass the DREAM Act of 2023!


Marjorie Taylor Greene casts heartless vote in pathetic display of apathy towards Turkish and Syrian earthquake victims
In a stunning display of immoral apathy, the QAnon congresswoman was just one of two House members to vote against a bipartisan resolution to mourn the 50,000 lives lost during the devastating earthquakes in Syria and Turkey. Given her rank and outspoken Islamophobia, it's not hard to put the pieces together here.

Take Action: Tell Congress to give free lunches for EVERY student!


photo
DeSantis signs bill that gives him more control of Disney’s special district

Meatball Ron is once again exploiting his gubernatorial powers to escalate his stupid war against the Mouse House. As payback for Disney's opposition to his deeply dangerous, homophobic "Don't Say Gay" bill, DeSantis signed a new bill that directs the state to take control of the Reedy Creek Improvement District, the government body that has given Disney unique powers in Central Florida for more than half a century. This is pure partisan hackery of the lowest form and is clearly engineered to send a signal to other companies: take a stand against the far-right MAGA agenda and the targeting of marginalized groups at your own financial peril.

Take Action: Tell Congress to ban partisan gerrymandering!


Chip makers will have to provide child care to tap President Biden’s huge $39 billion semiconductor industry fund
In a huge win for working Americans, the Biden administration announced it will require companies that tap $39 billion in funding for domestic semiconductor manufacturing to provide affordable child care for their workers. Biden's new regulations will mandate that firms receiving incentives under last year's Chips and Science Act build daycare facilities near new manufacturing sites or give workers money to pay the costs through existing local options. Elections matter, folks.


photo
Republicans caught pulling DISGUSTING stunt over train derailment

No Lie with Brian Tyler Cohen Unbelievable. Brian Tyler Cohen's videos are now in Spanish! If you have friends or family who speak Spanish and want to keep up with politics, please send them this link to subscribe to my channel. And if you want to help support the Spanish effort, you can also watch and subscribe just to get things moving in the algorithm. Every bit helps!


Documents from JPMorgan CEO Jamie Dimon sought in Jeffrey Epstein lawsuits
JPMorgan is facing renewed pressure to hand over documents from longstanding chief executive Jamie Dimon in litigation accusing the bank of keeping the late sex offender Jeffrey Epstein and his associates as customers despite numerous red flags. The dead pedophile's victims deserve justice, and justice won't be served until everyone who helped Epstein carry out his despicable crimes is outed and held accountable.


College debt relief program rests in the hands of nine wealthy and elite people
The Biden administration will go before the conservative-packed Supreme Court this week to argue in favor of the president's historic student debt relief program in what could prove to be one of the defining legal battles of the Biden years. In addition to the right-wing stranglehold over the court, the administration will face another daunting challenge — the justices simply aren't representative of the tens of millions of borrowers who could benefit from the relief. They are wealthy, powerful jurists and practitioners of law with little sense of the financial problems that plague average Americans on a daily basis. Some baseline pessimism would be understandable here.


Biden will back Ukraine for "as long as it takes," Sec. Yellen says in Kyiv
During her trip to the Ukrainian capital, Treasury Secretary Janet Yellen dispelled any possibility that President Biden might bow to Republicans and their increasingly pro-Russia rhetoric by cutting off aid to Ukraine. Stating that she brought the message directly from Biden himself, Yellen stated: "We will stand with Ukraine for as long as it takes."


Elon Musk becomes the richest person in the world again
It appears that not even ruining Twitter by flooding it with neo-Nazi bullshit and defending a shockingly racist, washed-up cartoonist can get in the way of Elon Musk accumulating vast sums of unearned wealth. The billionaire tech bozo has once again claimed top spot as the world's richest person — a title that should carry with it more shame than pride given the widespread suffering that could be alleviated if that money were put to better use. Billionaire tax when?


photo


The USA, today

The daily planet

Hope...

Want more hope? Subscribe to our favorite good news newsletter FREE.


Today’s Action: Tell The New York Times to stop their right-wing, anti-trans bias!

Editorial giant The New York Times has a clear prejudice when reporting on trans issues, one that’s unfortunately helping normalize transphobia in mainstream society. Make no mistake, rampant transphobia is killing trans people — they’re being murdered, they’re ending their lives, and they’re living in fear. We are witnessing what is increasingly being viewed as a transgender genocide, and instead of protecting this vulnerable community, major media outlets are signaling to red-state legislatures that further isolating and ostracizing trans people through extreme legislation will be tacitly or outright permitted. Donald Trump, the standard bearer of the morally bankrupt Republican Party, has promised to “punish” hospitals who offer life-saving gender-affirming care to trans children, should he somehow be reelected in 2024. The multifaceted war being waged on trans people is in full swing with fatal consequences. Why is The New York Times — an absolute titan of the industry — amplifying intolerance and allowing contributors to stoke anti-trans hate under its famed banner? It’s unconscionable.

More than 180 Times contributors have signed a letter demanding the company stop their clear editorial bias toward the trans community, and readers can join the call as well. The signatories state that the Times has “treated gender diversity with an eerily familiar mix of pseudoscience and euphemistic, charged language, while publishing reporting on trans children that omits relevant information about its sources” despite their editorial guidelines demanding all pieces be “free of any whiff of bias.” It’s a slap in the face to the LGBTQ+ community, and telling of the company’s place in the fight for true gender equality — that is, the wrong side of history.

Instead of publishing trans-exclusionary and misleading hate speech, The New York Times should use its massive platform to amplify the names and stories of every trans person murdered in America the past two months alone — Jasmine “Star” Mack, KC Johnson, Unique Banks, Zachee Imanitwitaho, and others we may never know about. Join the more than 180 Times contributors and demand The New York Times stop their hostile, anti-trans bias immediately!

PS — Please don't forget to sign the petition demanding Fox News suspend Tucker Carlson for calling for violence against teachers and LBGTQ+ people, and be sure to follow us on Twitter, Facebook, and Instagram.

 @advocacy | 1002 Hull St., Louisville, KY 40204 


Top News | 'He’s Not Going to Run Unopposed': Sanders Rejects Schumer for Majority Leader

                                                               LOTS OF POSTS IGNORED BY BLOGGER..... OR REMOVED ON THEIR WHIM! ALL POSTS ARE...